Summary
At 7.40%, Tallahassee mortgage rates sound high only next to the pandemic years. Measured against every month since 1971, today’s 30-year mortgage rate is back to normal.
The rate is normal. The payment is not. In about six weeks, the climb added $244 a month, about 8%, to the loan payment on a $600,000 home with 20% down.
If you are buying, the monthly payment you settle on before you shop matters more than it did in August. If you are selling, fewer buyers are signing contracts than normal, so your price has to match what your home is worth. If you own a home with a fixed-rate loan, one whose rate never changes, and plan to stay, your loan payment did not change. The payment the next buyer of your home would face went up, and when you sell, that buyer’s budget sets your price.
The numbers behind that:
- The 30-year rate rose seven weeks in a row, from 6.65% on August 20 to 7.40% on October 8, its highest since November 2023.
- Today’s rate sits a little below the average since 1971. Leave out the highest and lowest months, and it sits right at the typical rate.
- The climb added about $8 to every $100 of a buyer’s monthly loan payment in six weeks. Over a full year, the prices of everything else people buy rose less than half that much.
- Since 2000, the payment on a typical Leon County home has risen far faster than the prices of everything else.
- Most of this year’s climb came from the 10-year Treasury, the rate the U.S. government pays to borrow. The extra that mortgage lenders charge on top of it barely changed.
- Tallahassee buyers started pulling back in May. Fewer homes than normal went under contract in every month from May through September.
Are Tallahassee Mortgage Rates Back to Normal?
Freddie Mac, the government-chartered company that buys home loans from lenders, has recorded the 30-year rate every month since April 1971, 667 months in all. Set today’s 7.40% against that history, and it lands near the middle.
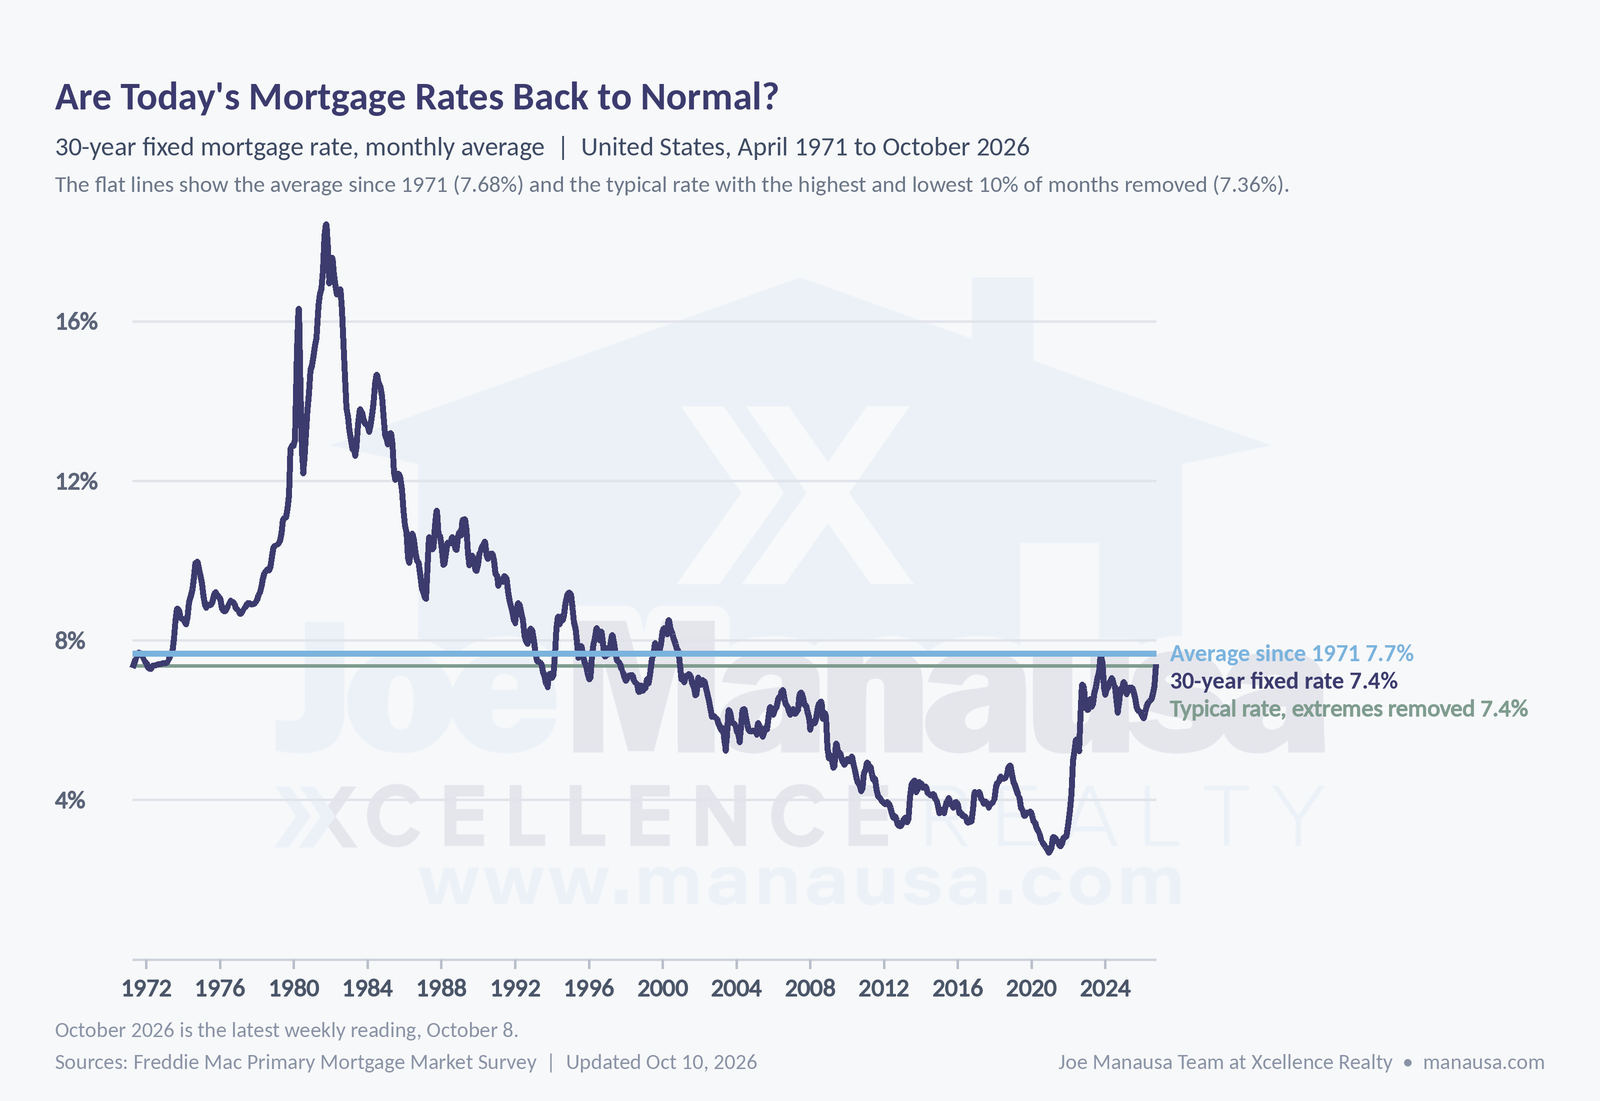
The average 30-year mortgage rate since 1971 is 7.68%. Today’s 7.40% sits 0.28 of a point below it.
An average can be pulled around by extreme months. Rates peaked near 18% in 1981 and fell below 3% in 2020 and 2021. Set aside the highest tenth and the lowest tenth of all months, and the typical rate in the middle is 7.36%. Today’s rate sits 0.04 of a point above it, close enough to call the two the same.
So why does 7.40% feel so high? Most buyers remember the pandemic years, when rates stayed under 3.7%. Those years were the exception, and measuring today against them makes a normal rate look like a crisis.
You can see each week’s national reading in the Freddie Mac weekly mortgage rate survey, the source for the weekly and monthly rates in this report. These are national averages, and Tallahassee buyers borrow in that same national market.
How Fast Did the 30-Year Mortgage Rate Climb This Fall?
Normal is one thing. Speed is another.
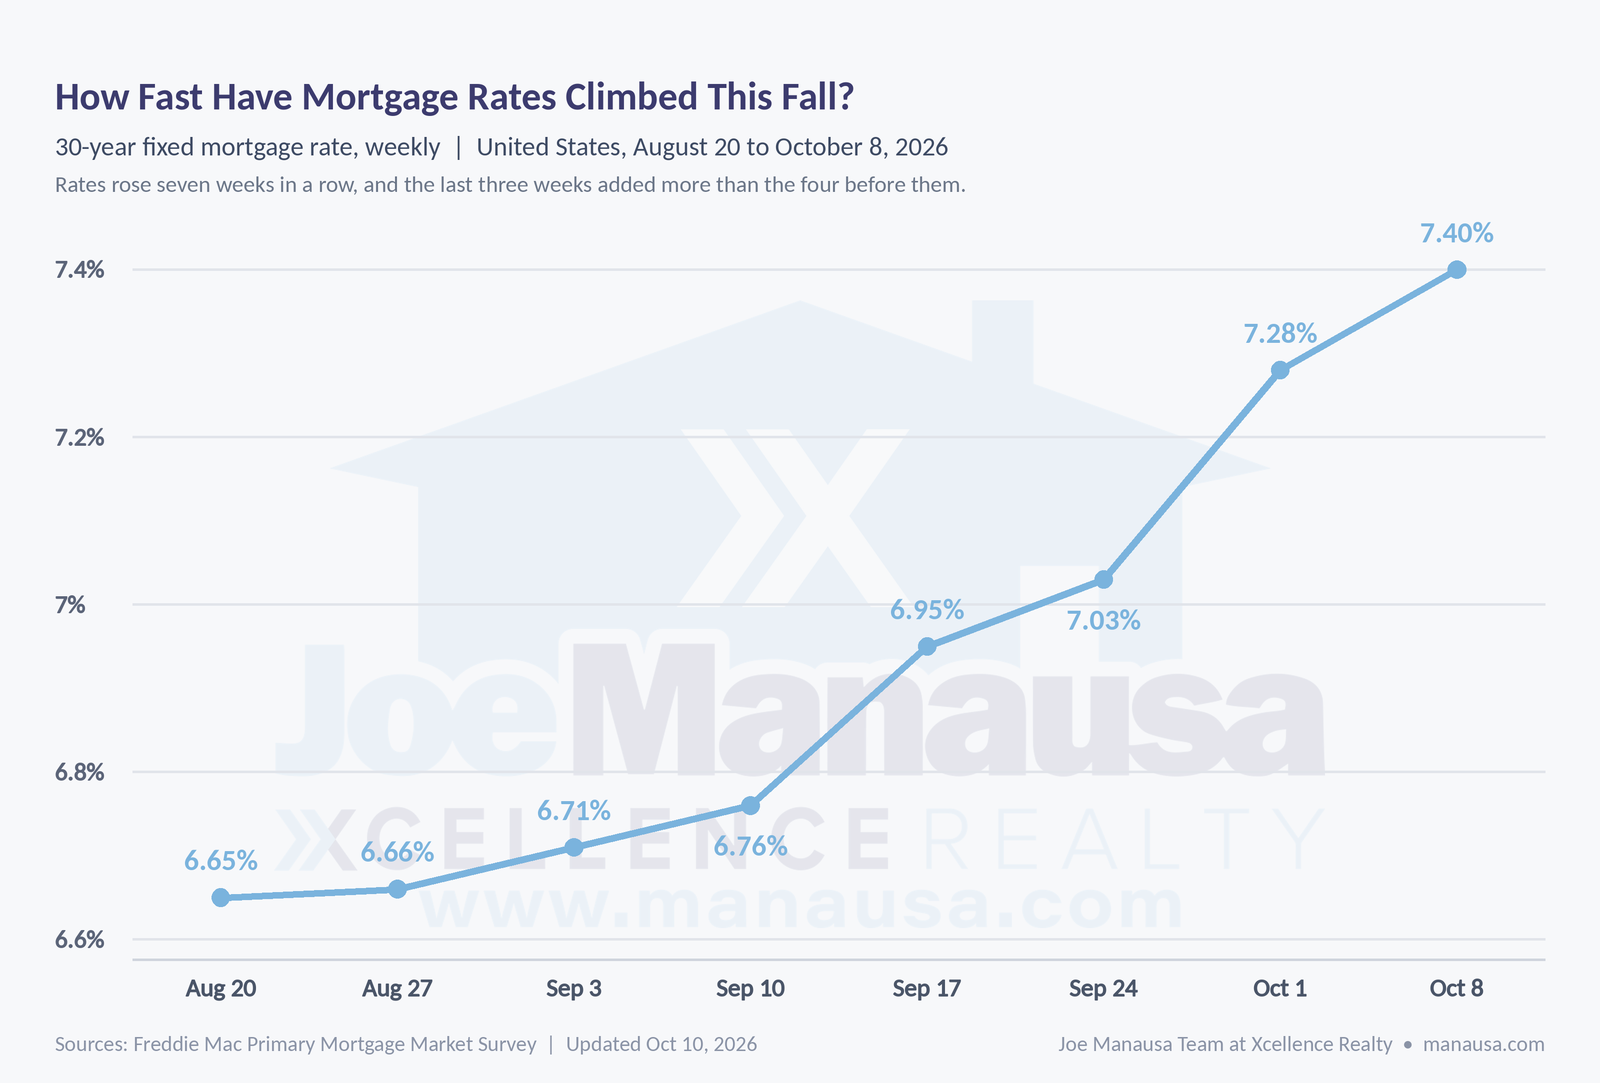
On August 20 the national average stood at 6.65%. It rose every week for seven weeks, to 7.40% on October 8, the highest since November 2023.
The last three weeks did most of the work. From September 17 to October 8 the rate added 0.45 of a point, while the four weeks before that added 0.30 of a point. A buyer who started shopping in late summer now faces a higher payment than the one they planned on.
The climb did not start this fall. It started in February, when the monthly average bottomed at 6.05%. It rose every month after that, reaching 6.44% in May and 6.86% in September.
What the Climb Adds to a Monthly Payment
Here is what the climb did to three common loans between August 27 and October 7. The rates come from the Optimal Blue mortgage rate indexes, which track the rates lenders lock each day, so they differ slightly from Freddie Mac’s weekly survey. The figures cover the loan payment plus any mortgage insurance the loan requires, before property taxes and homeowners insurance.
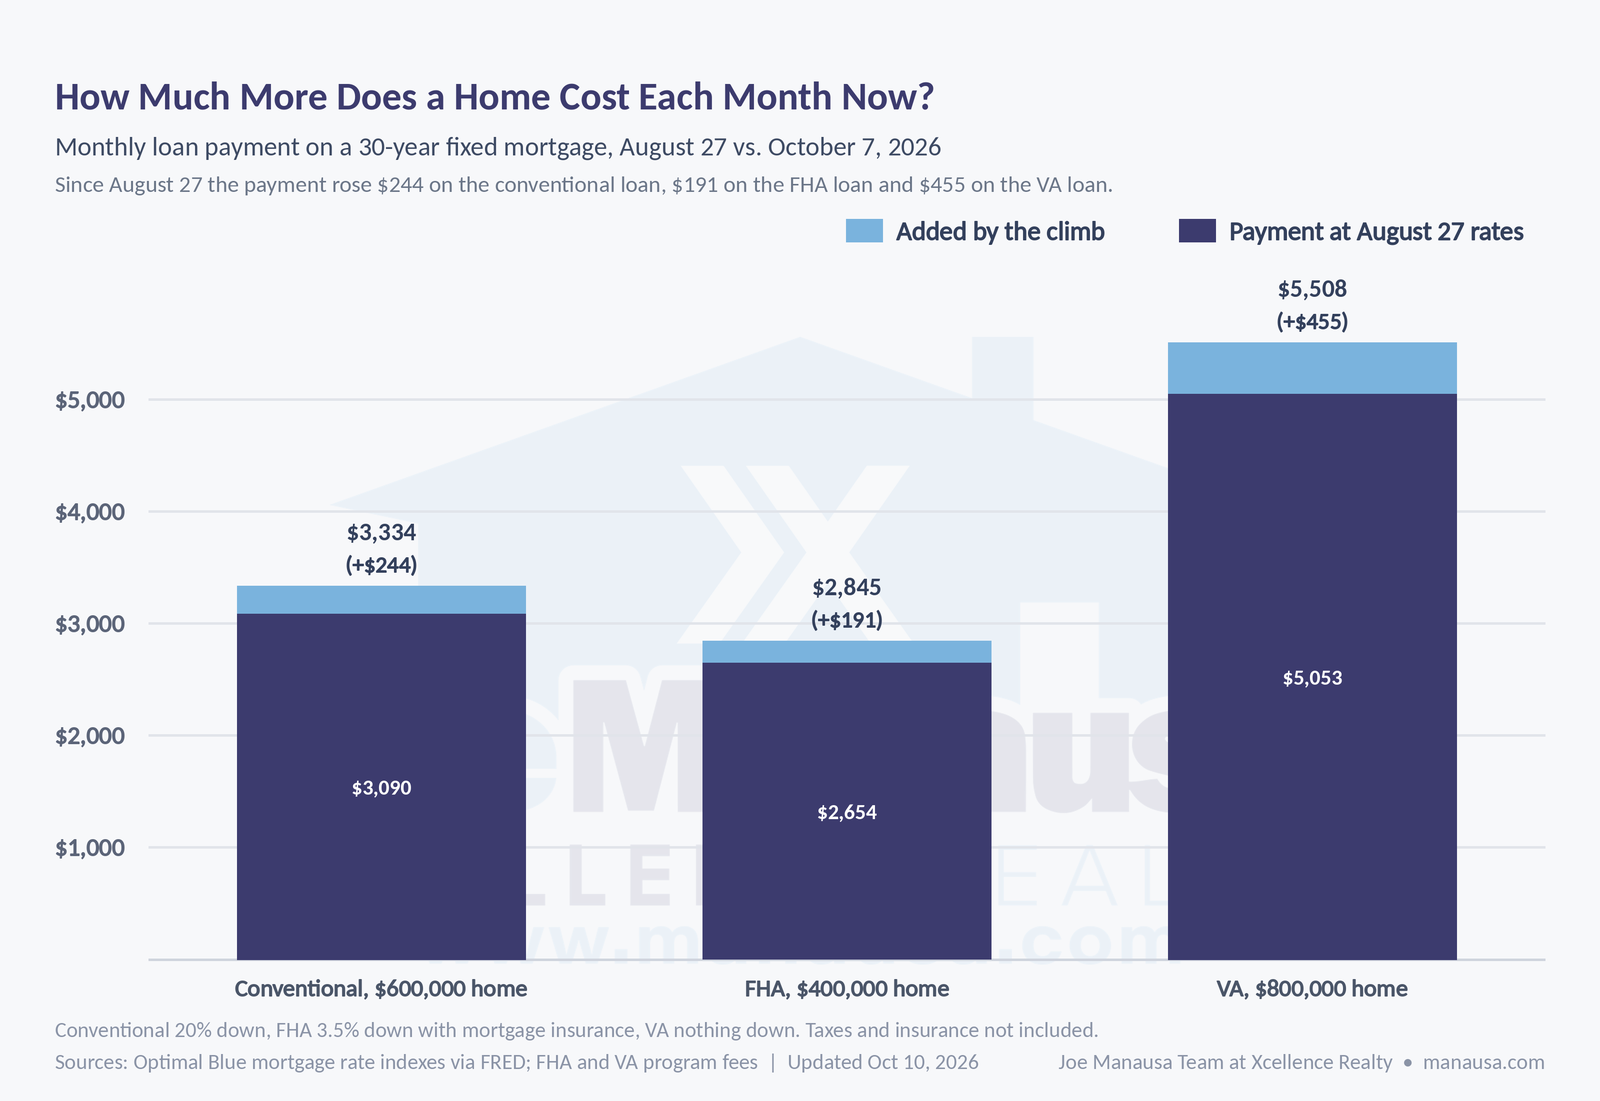
- Conventional loan on a $600,000 home with 20% down. A conventional loan is a standard home loan with no government backing. Here the loan is $480,000, and with 20% down it needs no private mortgage insurance. The rate rose from 6.678% to 7.433%, and the payment rose from $3,090 to $3,334, up $244 a month. On a fixed-rate loan, that extra cost stays for the life of the loan.
- FHA loan on a $400,000 home with 3.5% down. An FHA loan is backed by the federal government, which lets a buyer put less money down. In exchange, the buyer pays mortgage insurance, which protects the lender if a borrower stops paying. An upfront charge of 1.75% is added to the loan, bringing it to $392,755, and a yearly charge of 0.55% adds about $177 a month. The rate rose from 6.479% to 7.207%, and the monthly payment, including that $177 of mortgage insurance, rose from $2,654 to $2,845, up $191. Our post on FHA loans in Tallahassee explains when this loan fits.
- VA loan on an $800,000 home with nothing down. VA loans serve eligible veterans and service members. The 2.15% funding fee for a first-time VA loan is added to the loan, bringing it to $817,200, and the VA funding fee table shows the charge for other situations. The VA loan carries no monthly mortgage insurance. The rate rose from 6.291% to 7.130%, and the payment rose from $5,053 to $5,508, up $455 a month. Our post on VA loans for veterans covers how the loan works.
Across the three loans, counting the mortgage insurance on the FHA loan, the payment rose 7% to 9%. That might not sound like a lot until you set it beside everything else people buy.
Prices of everything except housing rose 3.6% over the full year through August 2026, according to the Consumer Price Index without shelter. A buyer’s loan payment rose more in six weeks than the prices of everything else rose in a full year.
Housing now takes a bigger share of what a household has left to spend each month.
We left housing out of that price measure on purpose. The government’s inflation figure tracks housing through rents, not mortgage payments, so it would blur the very cost this report is about. To see what today’s rate does to the payment on the house you have in mind, try our mortgage calculator.
Has the Cost of Buying a Home Outrun Everything Else?
Six weeks is a short window. Since 2000, the monthly loan payment on a median-priced Leon County home has outrun the prices of everything except housing. The median is the middle price, with half of sales above it and half below.
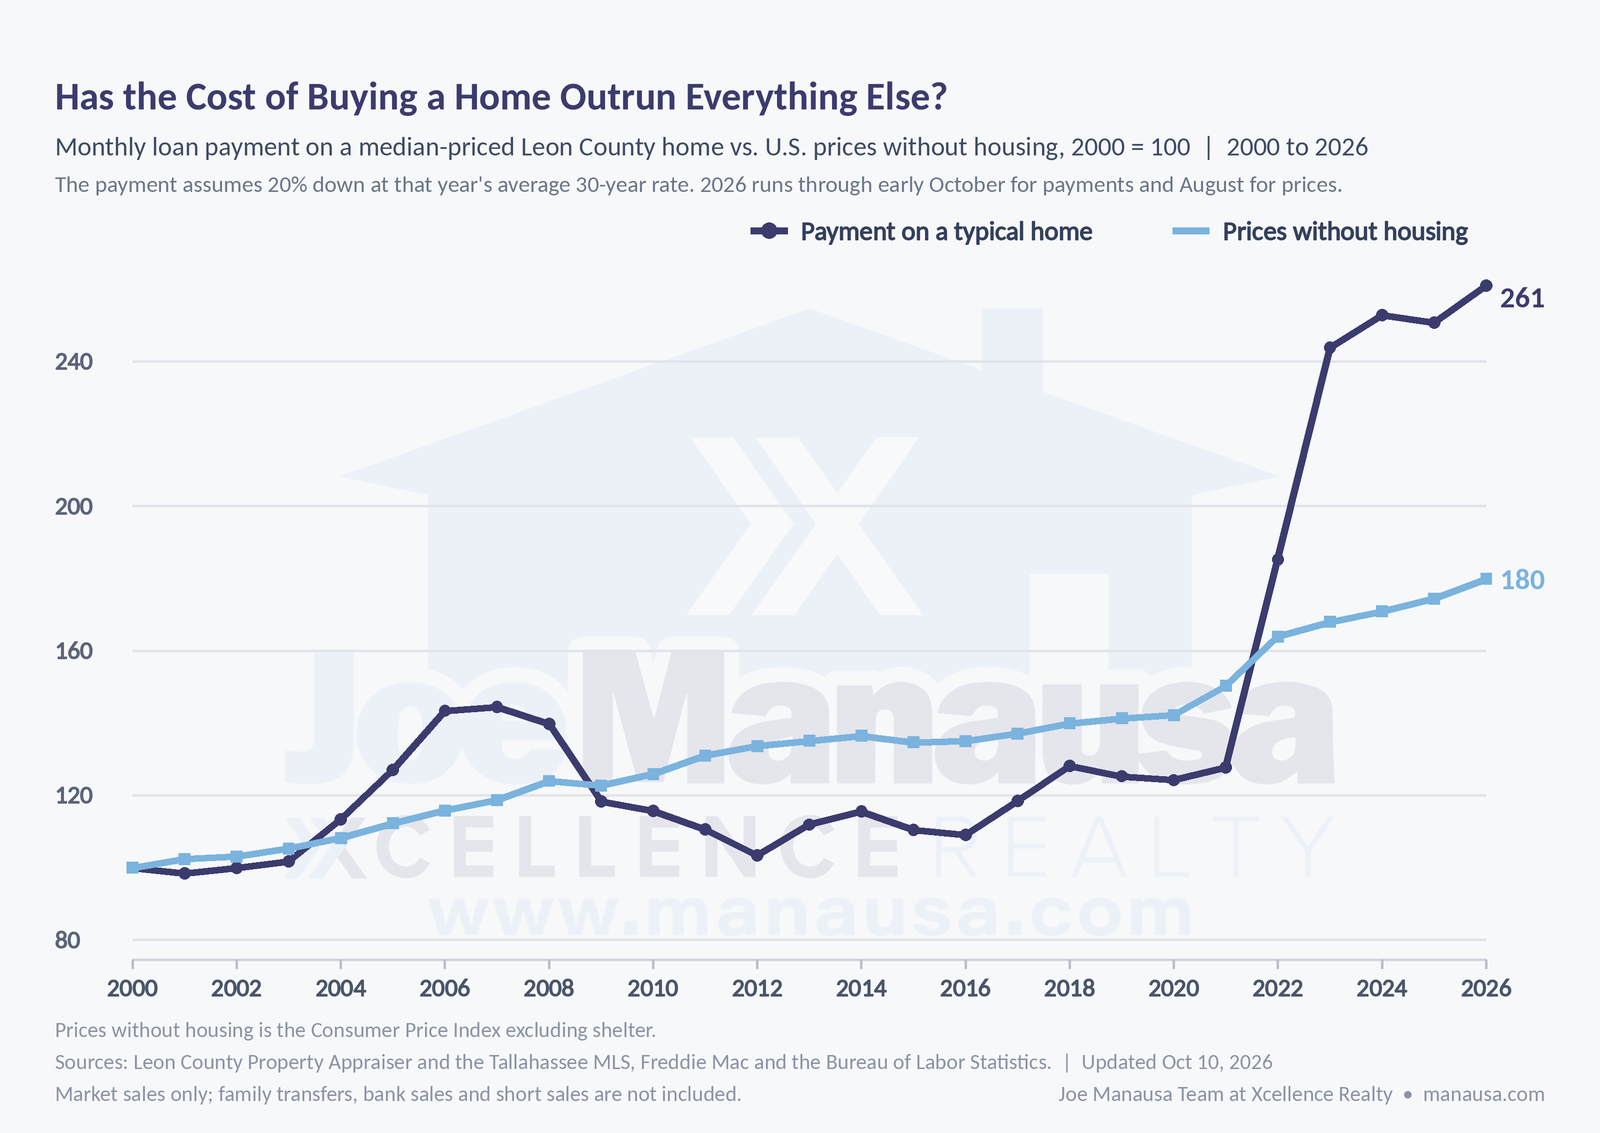
In 2000 the median Leon County home sold for $105,000. In 2026 so far, the median is $320,000. Those figures count houses, townhouses and condos sold on the open market.
With 20% down at each year’s average 30-year rate, the monthly loan payment on that median home was about $620 in 2000. Today it is about $1,618. The payment has far more than doubled.
A payment that cost $100 in 2000 now costs about $261. Everything else that cost $100 in 2000 now costs about $180. The payment has pulled well ahead of a household’s other bills.
The lines did not always look like this. From 2009 through 2021, low rates kept the payment line below the prices line. The gap opened in 2022, when rates climbed, and today it is wide.
So what income does that payment take now? Our report on the income needed to buy a home in Tallahassee answers that by ZIP code, and our affordability calculator shows where your own budget lands.
Why Did Mortgage Rates Climb?
Lenders set the 30-year mortgage rate by starting from the 10-year Treasury yield, the interest rate the U.S. government pays when it borrows money for 10 years. That is why the two rates rise and fall together.
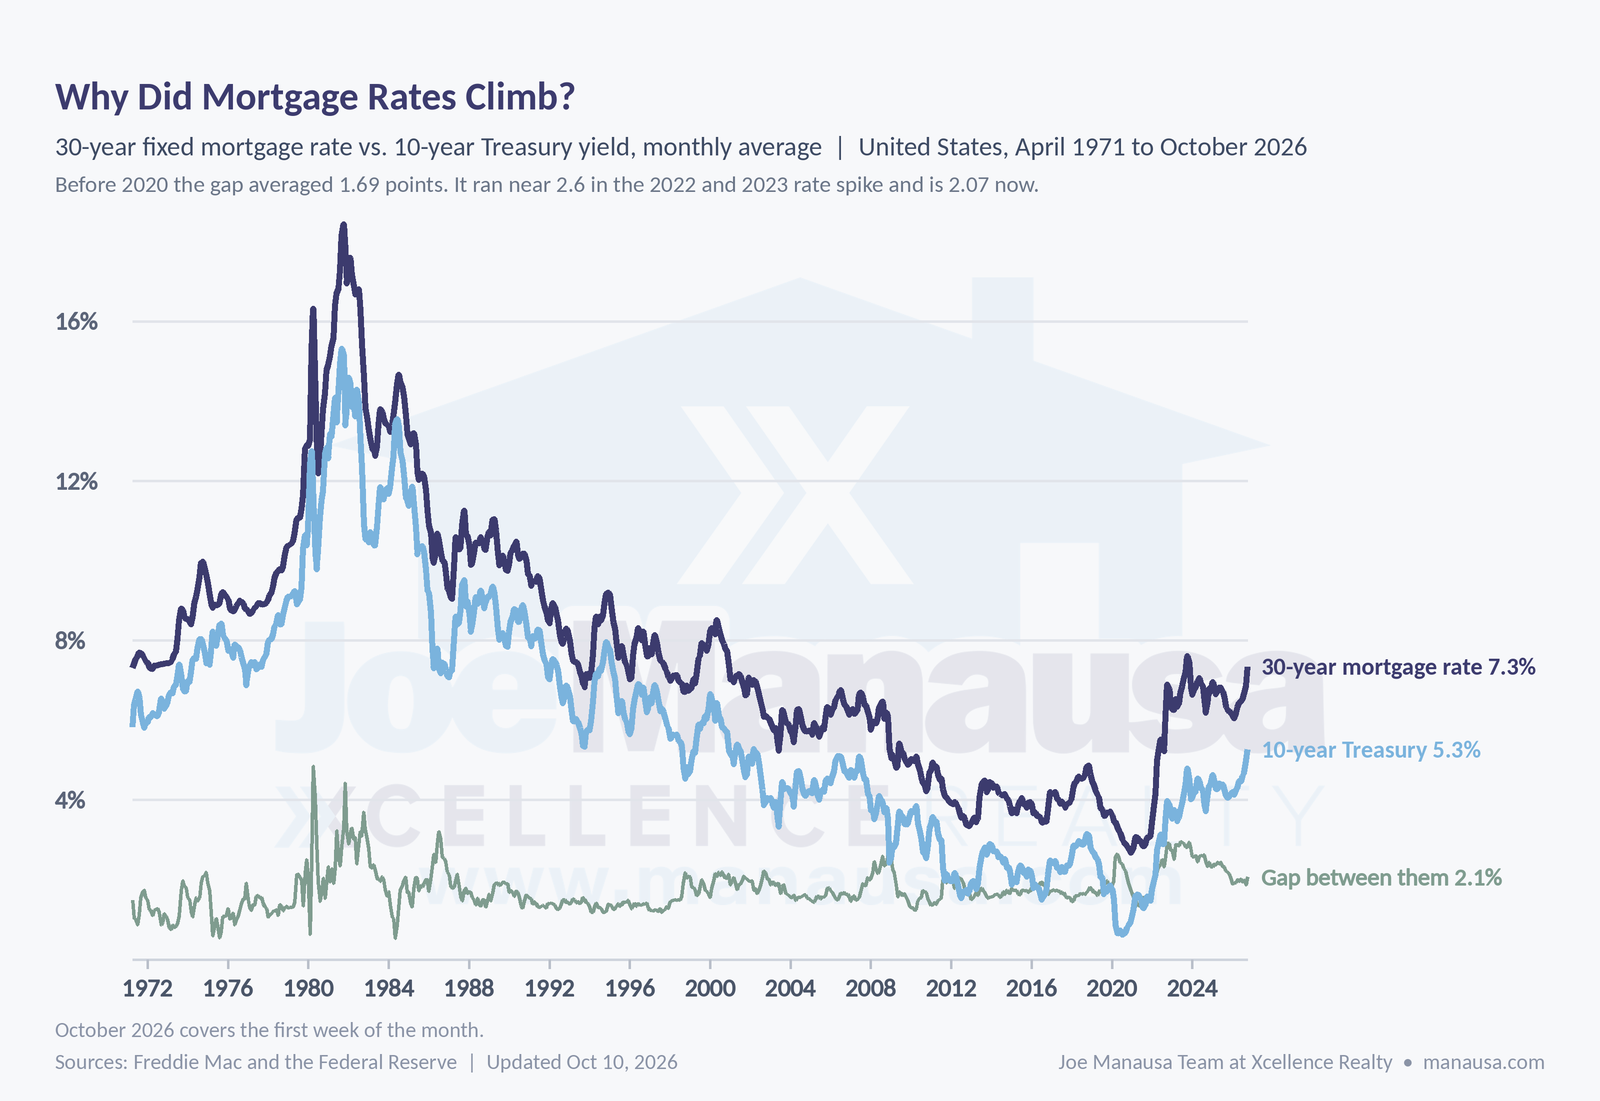
Since February 2026, the 10-year Treasury has risen 1.14 points, from 4.13% to 5.27%. Over the same stretch, the mortgage rate has risen 1.29 points, from 6.05% to 7.34%. These are monthly averages, and October so far covers only its first week.
The space between those two lines is often called the spread. It covers the lender’s costs, how eager investors are to buy mortgages, and the risk that a borrower pays the loan off early. An early payoff, by selling or by switching to a cheaper loan, cuts short the interest investors expected to earn. When that space is wide, borrowers pay more than the Treasury alone would explain.
Before 2020, the spread averaged 1.69 points. It ran near 2.6 points in 2022 and 2023, and it stands at 2.07 points now. Of the 1.29 points the mortgage rate has added since February, the Treasury accounts for 1.14 and the spread only 0.15.
Why did the Treasury rise? Investors who lend to the government for 10 years want a return that stays ahead of inflation, and overall inflation was 3.4% for the year through August 2026.
On September 16, the Federal Reserve raised its benchmark rate by a quarter point, to a range of 3.75% to 4%. The benchmark is the rate banks charge each other on overnight loans, and this was the Fed’s first increase since 2023. Its statement that day said inflation remains elevated.
The Fed does not set mortgage rates directly, but its moves shape what investors expect. Our post on how the fed funds rate affects mortgage rates walks through that link.
What Could Mortgage Rates Do Next?
Nobody knows where rates go from here. The useful question is what would have to happen for them to move.
The spread narrows. If the space between the mortgage rate and the Treasury returned to its pre-2020 average of about 1.7 points, the 30-year rate would sit roughly 0.3 to 0.4 of a point lower, even if the Treasury did not move at all.
The Treasury moves. This is the bigger unknown. With inflation above the Fed’s 2% goal and the Fed raising its rate, the Treasury yield could keep climbing. It could also turn lower if inflation cools.
What that means for your plan. Build it around the rate you can get today, not the rate you hope for. If rates fall later, that is good news your plan never had to count on.
Our report on the lock-in effect of rising mortgage rates explains why higher rates can make owners slow to sell, and our June 2026 report on the U.S. housing market and mortgage rates shows the national picture.
Have Tallahassee Buyers Pulled Back?
A higher rate shows up first in what buyers do. Each month, we compare the number of Leon County homes that went under contract, meaning a buyer and seller signed a contract, with the 2007 to 2025 average for that month.
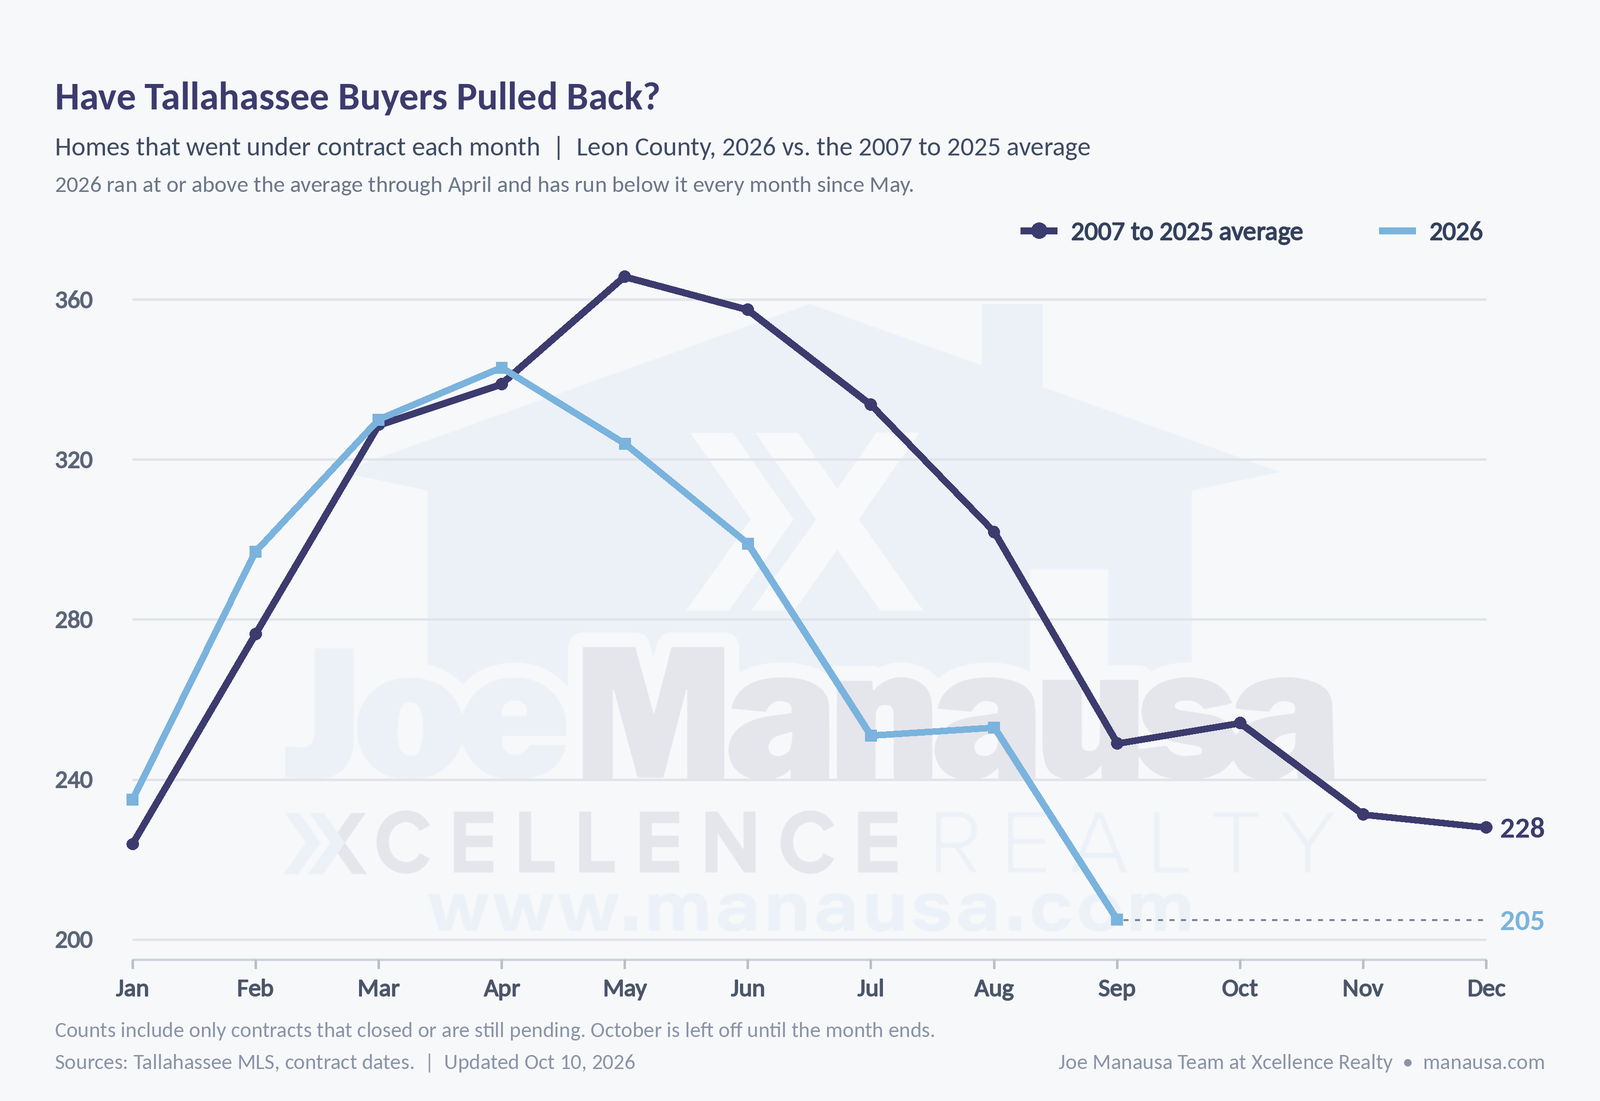
January through April ran at or above normal. May fell 11% below, and every month since has stayed below, with July the weakest at 25% under.
In September 2026, 205 homes went under contract, against a September average of 249. That works out to about 18 fewer contracts for every 100 in a normal September. For a seller, it means fewer buyers making offers on any one home.
Rates bottomed in February and had risen for three months, to a monthly average of 6.44%, by the time contracts fell below normal in May.
September ran 18% below normal, better than July’s 25%. The sharpest weeks of the climb started September 17, after many September contracts were already signed, so the count does not show their effect yet. October stays off the graph until the month ends, and that count will show whether the fall climb pushed buyers back further.
Fewer contracts mean each home waits longer for its buyer, as our report on homes taking longer to sell in Tallahassee shows. Our report on housing supply by ZIP code shows how many homes are for sale in your part of town.
What This Means if You Are Buying
On a $600,000 home with 20% down, the climb added $244 to the monthly loan payment. Plan for that before you shop.
- Set the payment before the house. An FHA buyer looking at a $400,000 home would now pay $2,845 a month, up from $2,654 in late August, including about $177 of mortgage insurance. Decide the payment you are comfortable with at today’s rate, then search only in the price range it allows.
- Remember that the rate is not the whole payment. Every payment in this report covers the loan and any required mortgage insurance, and property taxes and homeowners insurance come on top. Our October report on Tallahassee homeowners insurance covers that part of the bill.
- Pay for value, not the asking price. Compare the asking price with what similar homes nearby sold for. With 205 contracts in September 2026 against a September average of 249, sellers have more reason to listen to an offer built on those sales.
- Ask about the seller’s loan. Some VA loans can be taken over by the buyer, old rate and all. A seller who borrowed in 2020 or 2021, when rates stayed under 3.7%, could hand you a far smaller payment on the part of the price that loan covers. You would still need cash or a second loan for the rest. Our post on the assumable VA loan advantage explains when a buyer can take over a seller’s VA loan.
Once you know your payment, search Leon County homes for sale in the price range it allows.
What This Means if You Are Selling
With fewer buyers signing contracts than normal, your price and how many buyers see your home carry more weight than they did in the spring.
Pre-market the home. Pre-marketing means entering the home as a Coming Soon listing in the MLS, the shared database agents use to list homes for sale, and telling buyers about it before it is available to show, so interested buyers are already waiting on the day it is. With fewer buyers in the market, a home that only a few of them see may draw one offer or none. When several are waiting on launch day, they compete with each other instead of one buyer negotiating against you.
Social media is how the word spreads. Every share puts the home in front of buyers who were not searching yet, including friends of friends of the seller. Ask any agent you interview how widely their Coming Soon listings circulate before they go live. Our post on pre-marketing a home explains how it works.
Price for the buyer’s new payment. A buyer who planned on $3,090 a month in August now faces $3,334 for the same $600,000 home with 20% down. Many will shop a lower price range rather than pay more, so a home priced above its value loses the buyers it needs. Our recent report, Supply Is Back, But Sales Are Not, shows why.
Not every buyer needs a loan. Buyers who pay cash skip the rate question entirely, and you might be surprised how many of them there are. Our report on Tallahassee cash buyers shows how they fit into this market. Our page on selling a home lays out how we approach a sale from start to finish.
What Could Your Home Sell For?
Your price has to match what your home is worth, and that starts with a current number. This tool gives you an estimate from recent nearby sales.
Use that figure as a starting point, then weigh it against the buyer activity in this report.
Frequently Asked Questions
Is the 15-year mortgage rate lower than the 30-year rate? Yes. On October 8, 2026, the 15-year fixed rate averaged 6.73%, below the 30-year rate of 7.40% that same week. The monthly payment runs higher because the loan is paid off in half the time, but the buyer pays far less interest over the life of the loan.
How do today’s rates compare with a year ago? In October 2025, the 30-year rate was 6.30%. On a $480,000 loan, today’s 7.40% costs about $352 more a month than that rate would.
Is there a limit on the size of an FHA loan in Leon County? Yes. Leon County’s 2026 FHA loan limit is $541,287, which is why the $392,755 loan in our example fits under it. You can look up the limit for any county with the HUD FHA loan limit lookup.
Why not compare today’s rate with the pandemic years? Those years pull the picture out of shape. Leave out 2020 and 2021, when rates stayed under 3.7%, and the average since 1971 rises to 7.85%. Against that measure, today’s 7.40% sits even further below the long-run average.
Get the Weekly Market Report
The 30-year rate rose seven weeks in a row, and our weekly market report tracks what each move means for Tallahassee buyers, sellers and homeowners.
 Weekly Market ReportThe Tallahassee numbers local agents watch, in your inbox every Monday.Free. Unsubscribe anytime. Privacy policy
We Are Here to Help
What matters is what a rate change does to your payment, your price and your timing. You do not have to be ready to buy or sell to ask a question.
Related reading: Buying a home in Tallahassee | Our June 2026 affordability report | Leon County home prices and values | The best time to buy a home in Tallahassee
Send our team a note with the address you are watching, and a team member will tell you what today’s rates mean for that home.
Sources
- Weekly and monthly 30-year and 15-year rates: the Freddie Mac Primary Mortgage Market Survey, April 1971 to October 2026.
- Conventional, FHA and VA rates: the Optimal Blue mortgage rate indexes, including the Optimal Blue FHA rate index.
- Prices without housing: the Consumer Price Index excluding shelter from the U.S. Bureau of Labor Statistics.
- The 10-year Treasury yield: the Federal Reserve.
- Median prices: the Leon County Property Appraiser and the Tallahassee MLS, market sales only.
- Homes under contract: the Tallahassee MLS.
- FHA loan limits: HUD. The VA funding fee: the U.S. Department of Veterans Affairs.