
Weekly Special | June 30, 2025
Lock-In Effect Explained
I often refer to the rate lock-in effect that has stifled demand in the housing market, so I thought I would bring a graphic to demonstrate the significance of its impact.
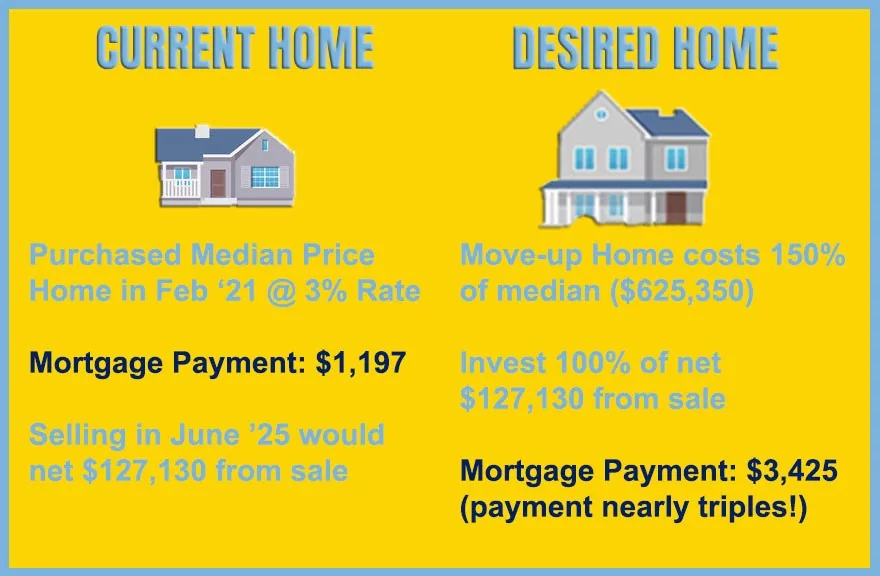
Suppose you purchased a median priced home for $355K in February 2021 and financed it with a 3% rate 30-year fixed rate loan. At the time, you and your spouse were pregnant with you first child.
Today, with 2 children and one on the way, you decide you want to move up to a home that is 50% more expensive than the median price today (the typical move up is +50% in value).
Take The Good With The Bad?
It’s not all bad news. That $355K home you bought will sell for $417K today, leaving you roughly $127K in equity that you can use towards your next home.
Unfortunately, due to sky-high prices, that next home will cost you $625K, so after closing costs and your equity contribution, you will need to finance $520K.
With interest rates now just below 7%, your principal and interest payment will jump from just under $1,200 each month to more than $3,400! Additionally, the additional taxes and insurance premiums you will pay means that you total monthly payment will triple if you decide to move up to the larger home.
So what do you do? You will soon be a family of five, in a home you purchased for three!
In my 34 years selling real estate, I have rarely seen a family that can handle a 3x change in their monthly housing cost. Do they stay in place, do they move to a lesser expensive home, or do they just wait it out? This is the conundrum facing many buyers who are part of the growing pent-up demand in the housing market.
The original one-page Weekly Special PDF is still available.
Get the Weekly Special Every Monday
Each Monday morning the Weekly Special takes one Tallahassee housing question, answers it with a chart of local sales, and explains what it means for your next move.
It is free, and you can unsubscribe any time.