
Weekly Special | April 17, 2023
Why Foreclosure Surge Is Unlikely
If you are looking for some kind of sign that no foreclosure crisis is looming, then I would point you to my recent study of homeowner equity in the US housing market.
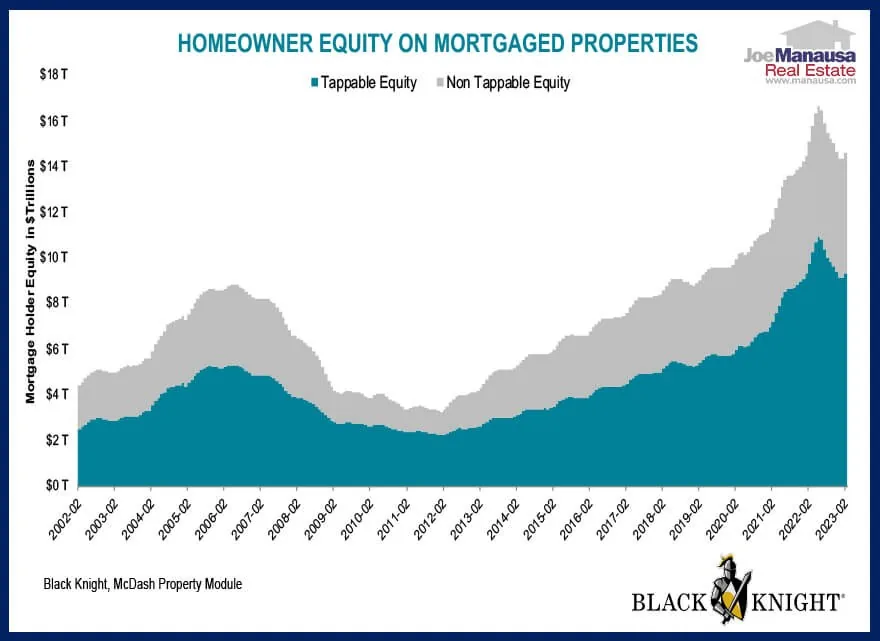
Total mortgage holder equity is down $2T (12%) from its 2022 peak, and the tappable equity (the share available to lend/borrow against while still maintaining a 20% equity cushion) has dipped by $1.6T (15%).
Despite the decline, $9.3T in equity remained available to tap as of the end of February, which is still up 56% ($3.4T) over the past three years.
To put those trillions of dollars into perspective, the average mortgage holder has $178K in tappable equity, down from more than $210K early last year but still $61K (54%) above the market average three years ago. Overall, homeowners still have strong equity cushions, despite recent declines.
This kind of information on homeowner equity explains why we SHOULD NOT expect elevated rates of foreclosures any time soon. People who get behind on their mortgage payments, for the most part, can sell their homes, pay off their debt, and walk away with cash.
A Real Housing Problem The problem in housing is affordability (or the lack thereof). People, due to recency bias, expect home prices to fall like they did in 2007. In reality, they should worry that home prices are going to continue higher at a frantic pace due to the limited supply of housing in our county, state, and country.
This issue went with a longer report on our blog: read the full blog post. The original one-page Weekly Special PDF is still available.
Get the Weekly Special Every Monday
Each Monday morning the Weekly Special takes one Tallahassee housing question, answers it with a chart of local sales, and explains what it means for your next move.
It is free, and you can unsubscribe any time.